High-Risk Clients Require Earlier Detection
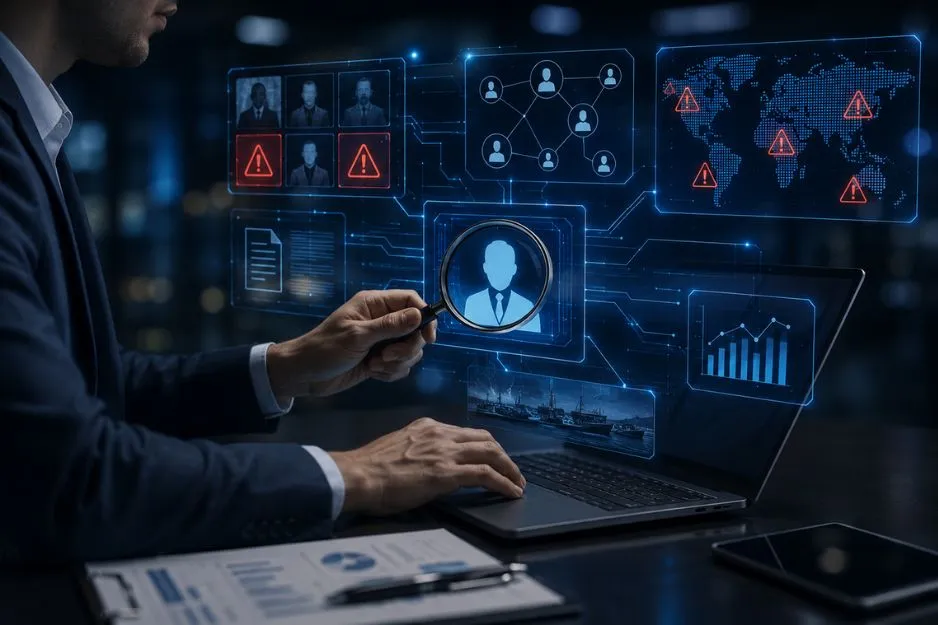
PEP and adverse media screening are becoming essential tools for DNFBPs making customer risk decisions in high-value and higher-risk transactions. Real estate brokers, dealers in precious metals and gemstones, auditors, accountants, corporate service providers, and legal professionals often deal with clients whose ownership structures, source of funds, or public exposure require deeper review.
FATF guidance on Politically Exposed Persons highlights that PEP relationships require additional AML/CFT measures because prominent public functions can be misused for corruption, bribery, or laundering illicit funds. For DNFBPs, this means screening cannot be treated as a one-time onboarding formality. It must support the full customer risk assessment process.
For additional regulatory context, see Designated Non-Financial Businesses and Professions.
PEP Risk Extends Beyond the Individual
PEP exposure is not limited to the person holding public office. Risk may also extend to family members, close associates, beneficial owners, corporate vehicles, and third parties connected to the transaction.
This matters because high-risk clients may not always appear directly in a file. A property buyer, gold customer, corporate structure, or advisory client may involve a beneficial owner or controlling party with political exposure. DNFBPs must therefore connect PEP screening with beneficial ownership verification, source of funds checks, sanctions screening, and enhanced due diligence.
A weak screening process can create serious gaps. If the firm identifies the legal customer but misses the real controller, the compliance decision may be incomplete.
Adverse Media Adds Context to Customer Risk
Adverse media screening strengthens risk assessment by identifying public-domain information that may not appear on sanctions lists or formal regulatory databases. Negative news linked to fraud, corruption, financial crime, sanctions evasion, organized crime, or serious regulatory misconduct can change how a customer should be classified and monitored.
However, adverse media must be interpreted carefully. Not every negative article creates AML risk. DNFBPs need to assess source credibility, relevance, timing, severity, and connection to the customer or beneficial owner.
Used properly, adverse media screening helps compliance teams decide whether standard due diligence is enough, whether enhanced due diligence is required, or whether suspicious transaction reporting should be considered.