Gold Moves Into a Digital Ownership Model
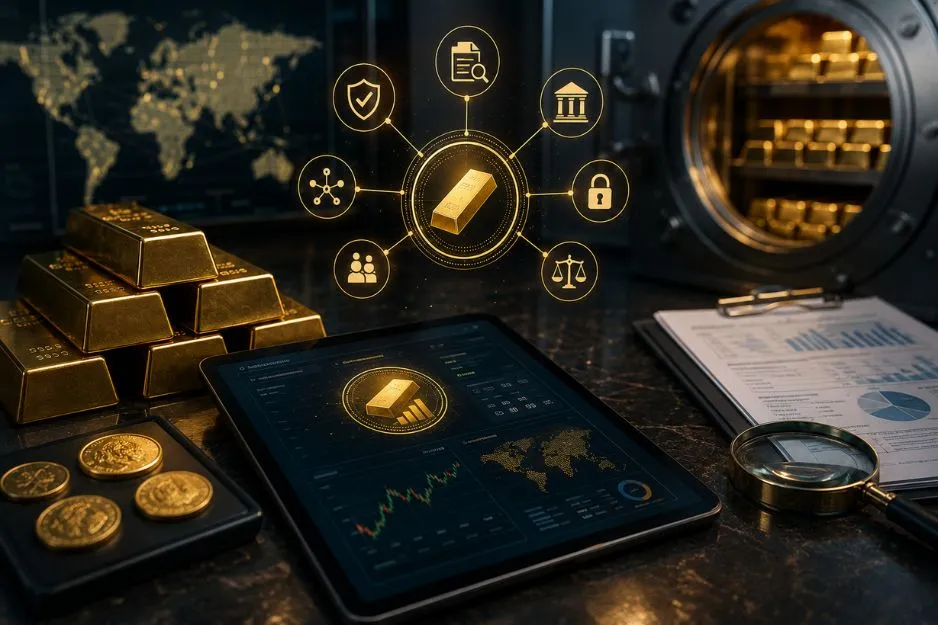
Digital gold is reshaping how value is stored, transferred, and verified across high-value markets. Instead of relying only on physical custody, some models use digital certificates, platform-based ownership records, or tokenised gold instruments linked to underlying physical reserves.
For precious metals firms and virtual asset businesses, this creates a more complex compliance environment. A transaction may involve gold custody, client wallets, platform records, reserve verification, payment flows, and cross-border counterparties. The compliance file must therefore explain not only who the customer is, but how ownership, value transfer, and underlying gold backing are controlled.
Custody and Reserve Evidence Become Central
Digital gold products depend heavily on trust in custody, allocation, and reserve integrity. If gold-backed tokens or digital ownership records are used, firms need evidence showing whether the underlying asset exists, where it is held, whether it is allocated, and whether customer balances can be reconciled.
VARA’s client virtual asset rules highlight the importance of client asset segregation, proof of reserves, and reconciliation for VASPs. While not every digital gold activity will fall under the same regulatory perimeter, these controls set an important benchmark for tokenised value models.
For DNFBPs dealing with precious metals, weak custody or reserve evidence can create serious compliance gaps. If ownership records are unclear, reserve claims are not verifiable, or client balances cannot be reconciled, the transaction becomes difficult to defend.
AML Controls Must Cover Commodity and Token Risk
Digital gold combines two risk environments: precious metals and virtual assets. This means firms must assess source of funds, source of wealth, beneficial ownership, sanctions exposure, transaction purpose, custody arrangements, and wallet or platform activity where relevant.
MoET’s AML/CFT framework places dealers in precious metals and gemstones within the DNFBP sector, while its responsible sourcing gold framework emphasizes risk identification, supply-chain controls, independent review, and reporting. VARA’s AML/CFT controls also reinforce the need for transaction monitoring, distributed ledger analytics, sanctions screening, and suspicious transaction reporting within virtual asset activity.
For compliance teams, the challenge is integration. Digital gold should not be reviewed only as a commodity transaction or only as a crypto transaction. It requires a joined-up risk view.