Introduction
As the UAE continues attracting international investors, entrepreneurs, expats, and high-net-worth individuals, DNFBPs are facing a more complex compliance environment around cross-border clients and high-value transactions. Real estate firms, company formation providers, auditors, legal advisors, precious metals dealers, and other DNFBPs increasingly need to understand not only who the client is, but whether the evidence behind the client's financial position can withstand scrutiny.
A recent analysis by AKW Consultants on UAE tax residency highlights an important risk area: residency status is not always determined by day-count rules alone. Dual residence, foreign tax exposure, double tax treaty considerations, and the wider factual pattern of a client's life can all affect how financial position and risk should be assessed.
For DNFBPs, this is not a tax matter alone. It becomes relevant when clients are involved in property purchases, business structuring, luxury asset transactions, precious metals trading, or investment activity. In these cases, assumptions are weak. Evidence must be clear, consistent, and defensible.
Reference: AKW Consultants
Why Evidence Matters in High-Value Client Files
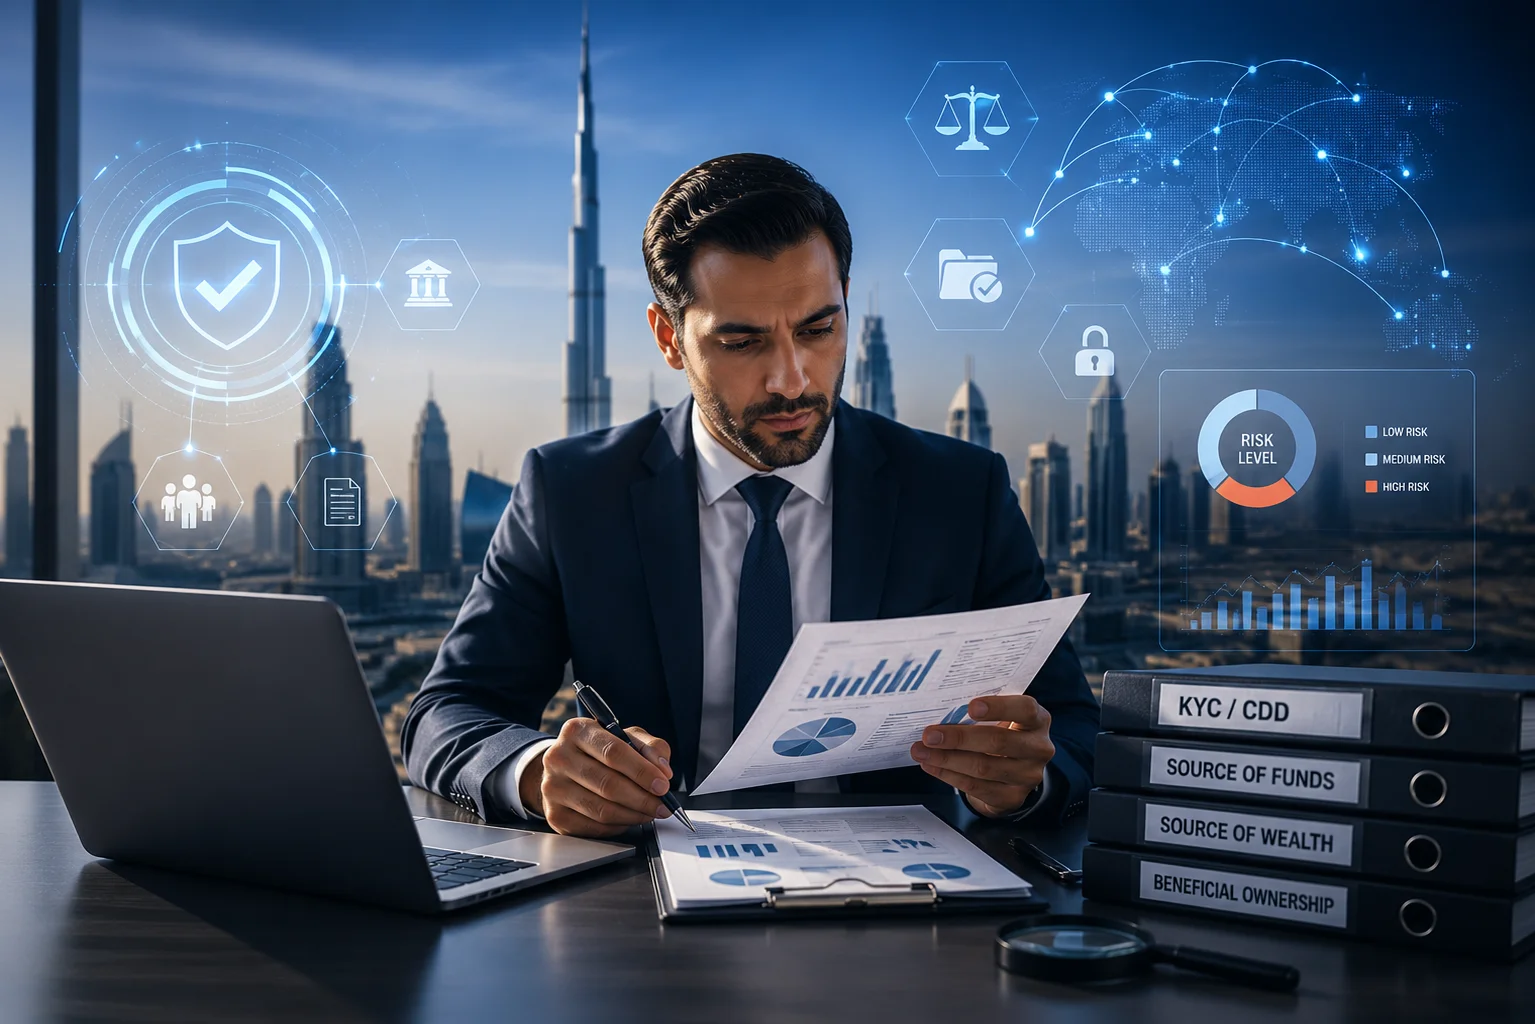
High-value transactions often involve multiple jurisdictions, layered ownership structures, overseas income, and complex wealth backgrounds. Weak documentation can create gaps in customer due diligence, source of funds checks, source of wealth verification, and beneficial ownership reviews.
Under the UAE AML/CFT framework, DNFBPs are expected to apply risk-based controls, maintain proper records, and strengthen compliance oversight across higher-risk client relationships. This means firms must move beyond basic form collection and build stronger evidence trails that support onboarding decisions, transaction approvals, and internal escalations.
Evidence-based compliance helps firms justify why a client was accepted, why a transaction was processed, and whether unusual activity required further review or suspicious transaction reporting. Without this level of documentation, compliance files can appear incomplete even when checks were performed.